What Is California’s Pure Comparative Negligence Rule?
In tort law, negligence rules determine how financial responsibility is divided when more than one party contributes to an accident. Across the United States, states generally follow one of three frameworks: contributory negligence (where being even 1% at fault bars any recovery), modified comparative negligence (where recovery is barred once a victim reaches 50% or 51% fault), or pure comparative negligence.
California follows the pure comparative negligence standard, established by the California Supreme Court in the landmark 1975 decision Li v. Yellow Cab Co. and rooted in California Civil Code Section 1714. Under this rule, a plaintiff’s total financial recovery is simply reduced in direct proportion to their assigned percentage of fault, with no upper cutoff. Whether a jury or insurance negotiation assigns you 10% of the blame or 80% of the blame, you are still legally entitled to collect the remaining percentage of your damages from the other negligent party.
How Shared Fault Is Calculated in a San Francisco Settlement
When pure comparative negligence applies to a personal injury claim, two distinct calculations take place: first, determining the total dollar value of your economic and non-economic damages (medical bills, lost income, future rehabilitation, and pain and suffering); and second, assigning a percentage of fault to every involved party. Your net settlement is calculated by subtracting your fault percentage from the gross value of your damages.
Consider a hypothetical San Francisco collision where your total documented damages equal $200,000:
| Your Assigned Fault (%) | At-Fault Party’s Share (%) | Gross Case Value | Your Net Settlement Recovery |
|---|---|---|---|
| 0% (No Fault) | 100% | $200,000 | $200,000 |
| 20% (Minor Contribution) | 80% | $200,000 | $160,000 |
| 50% (Equal Shared Fault) | 50% | $200,000 | $100,000 |
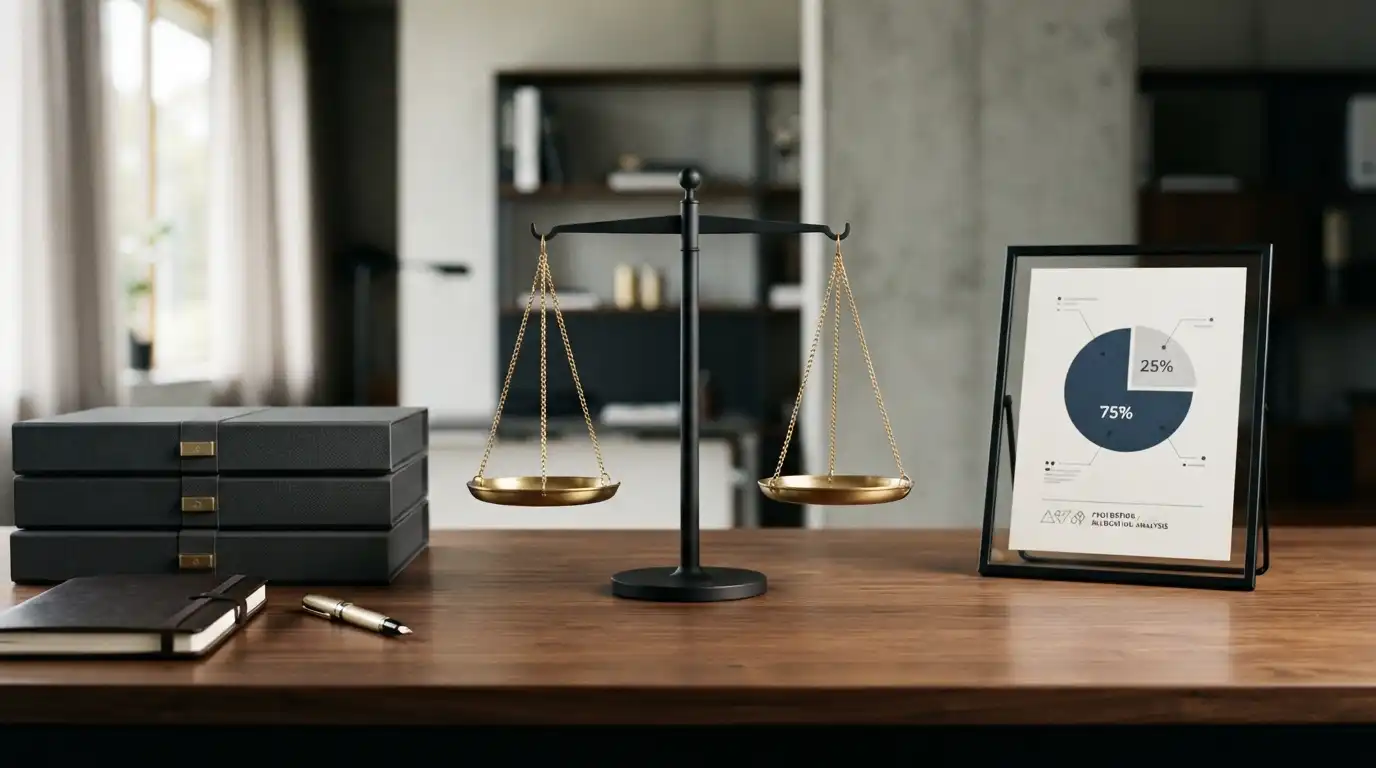
| 75% (Majority Fault) | 25% | $200,000 | $50,000 |
Notice how every single percentage point translates directly into thousands of dollars. In a $200,000 claim, shifting just 15% of blame onto your shoulders reduces your payout by $30,000. That financial reality explains why insurance carriers invest heavily in fault-shifting tactics from the moment a claim is opened.
Common San Francisco Scenarios Where Comparative Fault Arises
Because San Francisco combines steep hills, dense pedestrian corridors, protected bike lanes, Muni transit right-of-ways, and heavy rideshare traffic, multi-factor accidents happen every day. Insurance adjusters frequently raise comparative negligence arguments in several local scenarios:
- Left-Turn Intersection Collisions: A driver making an unprotected left turn across oncoming traffic on Geary Boulevard generally bears primary liability for failing to yield. However, their insurer may argue that the oncoming driver was speeding or accelerated to beat a yellow light, seeking a 20% to 30% fault reduction.
- Pedestrian Crosswalk Incidents: Under the California Vehicle Code, drivers must exercise due care toward pedestrians. Yet if a pedestrian stepped off the curb mid-block or crossed against a flashing “Don’t Walk” signal while distracted, insurers will attempt to apportion partial blame to the pedestrian.
- Bicycle and E-Bike Dooring or Lane Crashes: Cyclists struck by a driver opening a car door or merging into a Market Street bike lane are occasionally accused of riding too fast for conditions, lacking proper nighttime lighting, or failing to wear a helmet (though helmet use only affects head-injury mitigation arguments, not crash causation).
- Multi-Vehicle Chain-Reaction Pileups: Sudden stops on the Bay Bridge or Highway 101 often involve three or more vehicles, where each driver’s insurer points fingers at adjacent motorists to divide liability across multiple policies.
How Insurance Companies Weaponize Comparative Negligence
During pre-litigation settlement negotiations, there is no judge or jury assigning official percentages. Instead, fault allocation is a negotiation between your legal counsel and the insurance adjuster—guided by what a San Francisco jury would likely decide if the case went to trial. Adjusters routinely inflate a victim’s alleged fault by relying on incomplete police reports, cherry-picked witness statements, or recorded phone interviews taken before the victim has spoken with an attorney.
Even if an investigating SFPD officer issues a traffic citation or notes a contributing factor on a collision report, that administrative opinion is not the final word in a civil injury claim. Civil liability turns on admissible evidence, statutory duties of care, and expert reconstruction.
Practical Steps to Protect Your Settlement From Unfair Blame
If you are injured in a San Francisco accident where fault may be disputed, taking strategic steps early can prevent an insurer from artificially inflating your share of responsibility:
- Decline Recorded Statements to the Other Insurer: Insurance adjusters are trained to ask leading questions—such as “Could you have braked sooner?” or “Did you see the vehicle before impact?”—designed to manufacture admissions of partial fault.
- Preserve Digital and Video Evidence Immediately: Surveillance footage from corner businesses, Muni buses, Tesla Sentry Mode cameras, and residential doorbells in San Francisco is often overwritten within days. Securing video quickly can objectively disprove exaggerated blame-shifting claims.
- Document Sightlines and Road Conditions: Photograph obstructed stop signs, faded crosswalk markings, illegal curb parking near intersections, and traffic signal timing cycles right after the crash.
- Seek Prompt, Consistent Medical Care: Gaps in treatment allow insurers to argue that your own negligence worsened your medical outcome, a defense known as failure to mitigate damages.
Navigating Complex Fault Disputes in the Bay Area
California’s pure comparative negligence rule exists to ensure fairness—guaranteeing that an injured person is never left empty-handed simply because an accident involved split-second human imperfection. At the same time, because every percentage point directly impacts your net compensation, allowing an insurance company to dictate fault unchallenged can cost you tens of thousands of dollars.
If an insurer is trying to blame you for a collision in San Francisco, consulting with an experienced local personal injury attorney—and reviewing resources from the State Bar of California—can help you gather reconstruction evidence, push back against inflated fault assessments, and pursue the maximum recovery available under California law.